AUZ - Neighbour $2BN Sunrise announces Final Investment Decision on scandium project
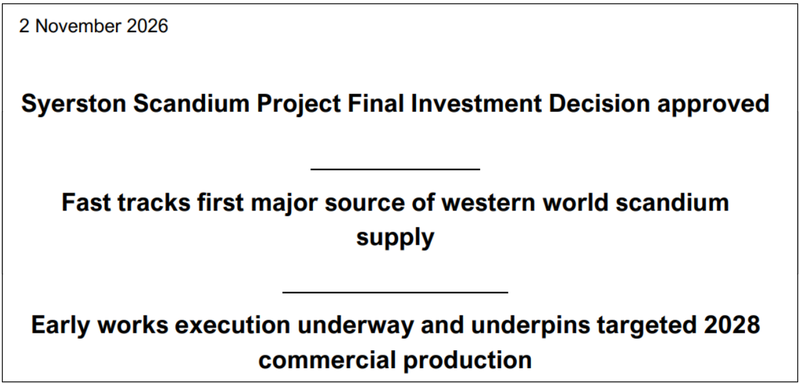
Our critical minerals Investment Australian Mines (ASX: AUZ) just had its next door neighbour approve a Final Investment Decision (FID) on the world's first primary scandium mine.
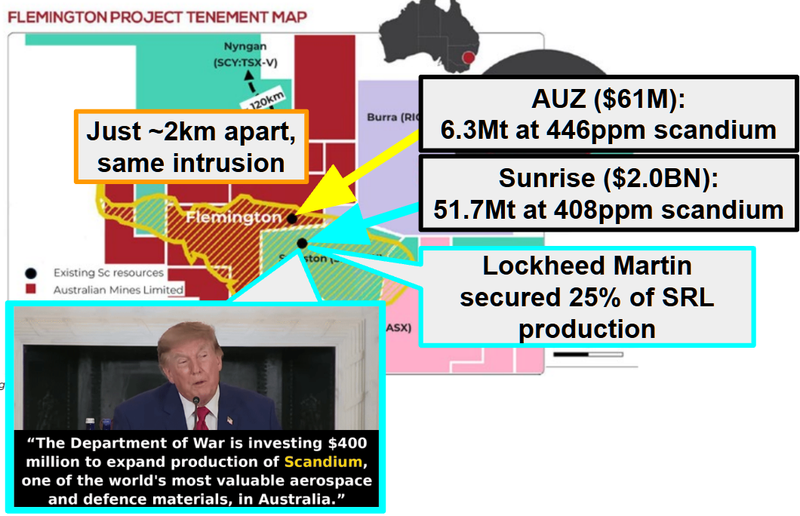
That is $2BN Sunrise Energy Metals - backed by Billionaire Robert Friedland AND by a US$400M conditional loan from the US Department Of War…
Which also happens to sit on the same geological intrusion as AUZ’s project:
(source)(source)(source)(source)
Sunrise is now aiming to have its project in production by H2-2028, ramping up to 60 tonnes per annum of high purity scandium oxide.
(source - Sunrise Energy Metals announcement)
We think the FID is good news for AUZ because:
1. AUZ’s project sits directly on the same geological intrusion that hosts Sunrise’s project.
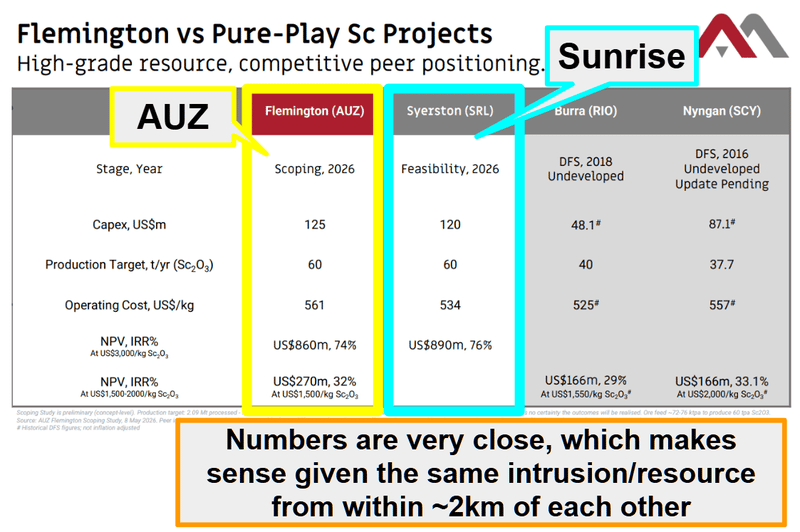
The big positive - AUZ’s resource is actually higher grade than Sunrise’s…
(source)
2. There is a proven playbook to getting a scandium project developed - studies, government backed funding, an offtake deal, leading to FID.
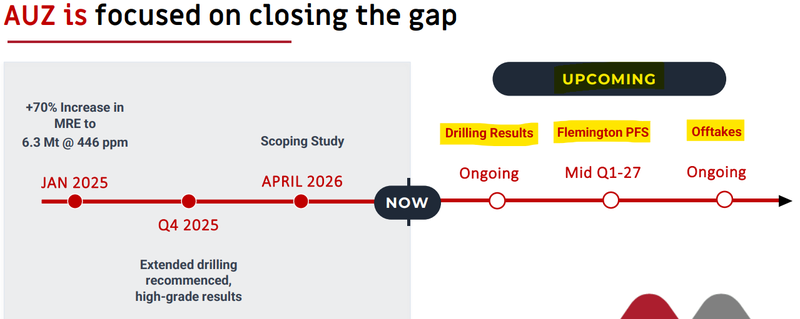
AUZ is at an earlier stage BUT is following in Sunrise’s footsteps.
Currently the main differences between Sunrise and AUZ from an asset perspective are:
1. Study stage - Sunrise has a Definitive Feasibility Study and an Ore Reserve.
🚨 AUZ has a Scoping Study, with a Pre-Feasibility Study due in mid-Q1 2027. (source)
2. Offtake and funding - Sunrise has a conditional US$400M loan commitment from the US government AND an offtake option with defence contractor Lockheed Martin.
🚨 AUZ has offtake discussions “ongoing” and no government funding/support (YET).
3. Corporate - Sunrise is re-domiciling to the US and going for a primary NASDAQ listing.
🚨 AUZ is ASX listed for now and is only also listed on the OTCQB (no mainboard US listing YET).
4. Size versus grade. Sunrise’s resource is ~8x the tonnage.
🚨 AUZ’s is the higher grade (446ppm vs 408ppm) with a simpler three-pit mine plan versus Sunrise’s 13 planned pits.
5. ✅ Scale - Both are planning production of scandium at ~60 tonnes a year - but AUZ’s PFS is also assessing 120 and 180 tonne a year cases. (source)
Here are some upcoming catalysts that AUZ is doing to close the gap:
(source)
3. Scandium demand keeps growing and Chinese exports have all but ceased.
Scandium's end uses (fuel cells powering AI data centres, aerospace alloys, semiconductors) keep growing.
There NYSE listed Bloom Energy, US$60BN capped that uses scandium to make solid-oxide fuel cells that give AI data centres on-site power without grid involvement.
Each of those fuel cells is ~10% scandium oxide. (source)
Bloom says it believes it is “the world’s largest consumer of scandium oxide” (source) - and we have seen estimates that it swallows up ~74% of global demand. (source)
A few weeks ago Bloom announced a 702MW fuel cell installation in Wyoming for Google. (source)
And a few weeks before that, Bloom did deals with Oracle for up to 1GW and up to 2.8GW - which on its own would need ~114 to 167 tonnes of scandium oxide.
For context - the entire world produced ~80 tonnes of scandium oxide last year - SO THAT one deal would take ~2 years of world consumption. (source)
(source)
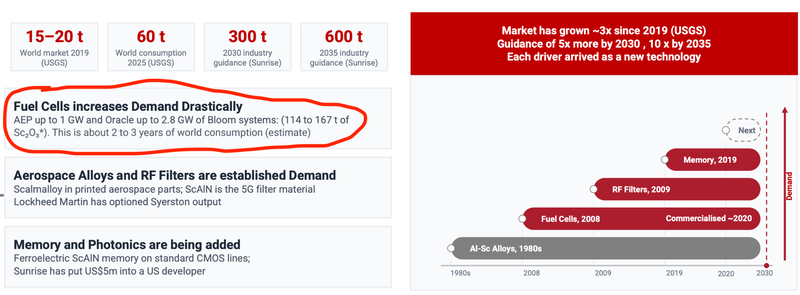
There are also other key use cases, particularly in special metal alloys, in the aerospace industry scandium can be added to make metal alloys stronger and lighter.
So no wonder $209BN capped Lockheed Martin has been signing up future supply, because currently there isn’t exactly any Western supply chain:
(source)
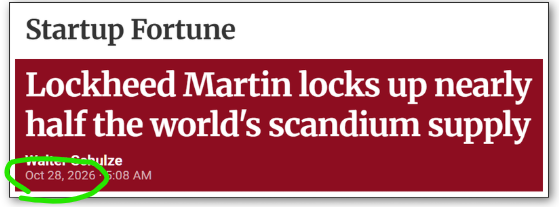
Lockheed Martin is the world’s largest defence contractor by revenue, it’s the company that builds F-35 fighter jets and PAC-3 missiles and it has an offtake option deal with AUZ’s direct neighbour Sunrise.
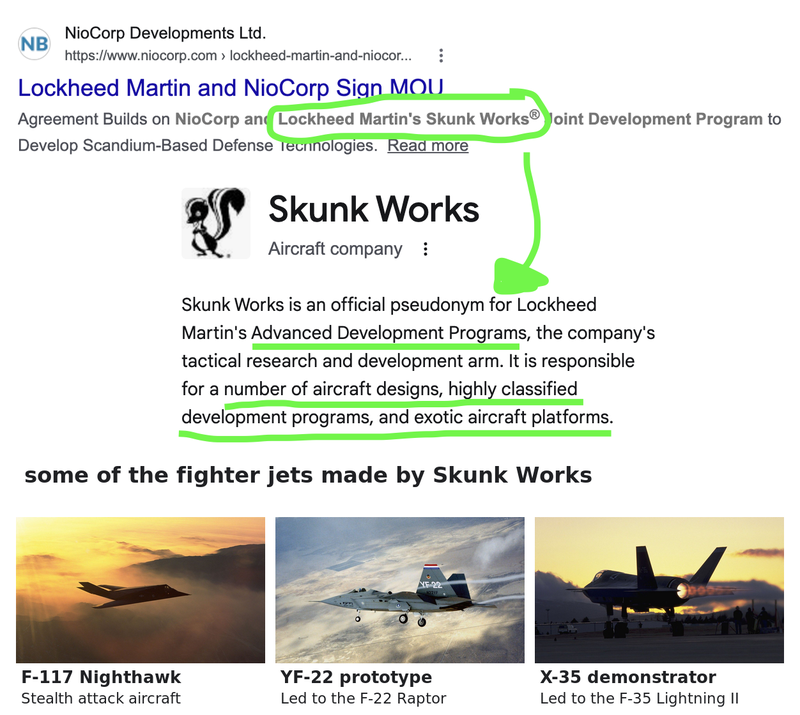
In August, Lockheed Martin made a deal with another scandium company based in the US as part of its “Skunk Works joint development program” (source) being partially funded by a US$10M Department of War grant. (source)
Skunk Works is the Lockheed division that built the U-2, the SR-71 Blackbird and the F-117 stealth fighter - i.e. the “secret-projects” shop.
We have previously written about the AI data centre demand story for the critical metal scandium.
However in parallel, aside from data centres, it looks like Lockheed is cooking something big up in the military space too (akin to what the Soviets did with their military in the 70’s and 80’s)
We wrote more on this last week in a Deep Dive article here: AUZ: Why is our scandium Investment running on strong volumes and (almost) no news?.
What we want to see next from AUZ
🔄 Pre-Feasibility Study for scandium project
We think this could be the next major catalyst for AUZ, so we want to see AUZ progress its scandium project through to being development ready.
The next major catalyst here being a Pre Feasibility Study (PFS)
Here are the milestones we are tracking:
✅ PFS formally commenced and fast-tracked (May 2026)
✅ Specialist PFS consultant team appointed (September 2026)
🔄 Metallurgy, geotech, tailings, environment and water studies
🔄 Assessment of the 120tpa and 180tpa scale-up cases
🔲 PFS completed (mid-Q1 2027)
🔲 Drilling to grow its scandium resource
We want to see AUZ drill out and grow its scandium resources - so that the market can start to make stronger comparisons between AUZ and Sunrise’s asset.
Here are the milestones we are tracking:
🔄 Drilling approvals (lodged - drilling to start once received)
🔲 Drilling commences (~50 holes / ~1,250m)
🔲 Drilling results
🔲 Corporate/commercial progress for scandium asset
We also want to see AUZ execute the Sunrise playbook and land some (or all) of the following:
🔄 Offtake / strategic partner discussions
🔲 First offtake, MOU or government-linked funding
🔲 Get interest from US investors OR get listed in the US
🔲 Name change to First Scandium approved (AGM, 24 November)